Closing Costs in Los Cabos: What Foreign Buyers Actually Pay Before Getting the Keys
 Buyer's Guide · Los Cabos
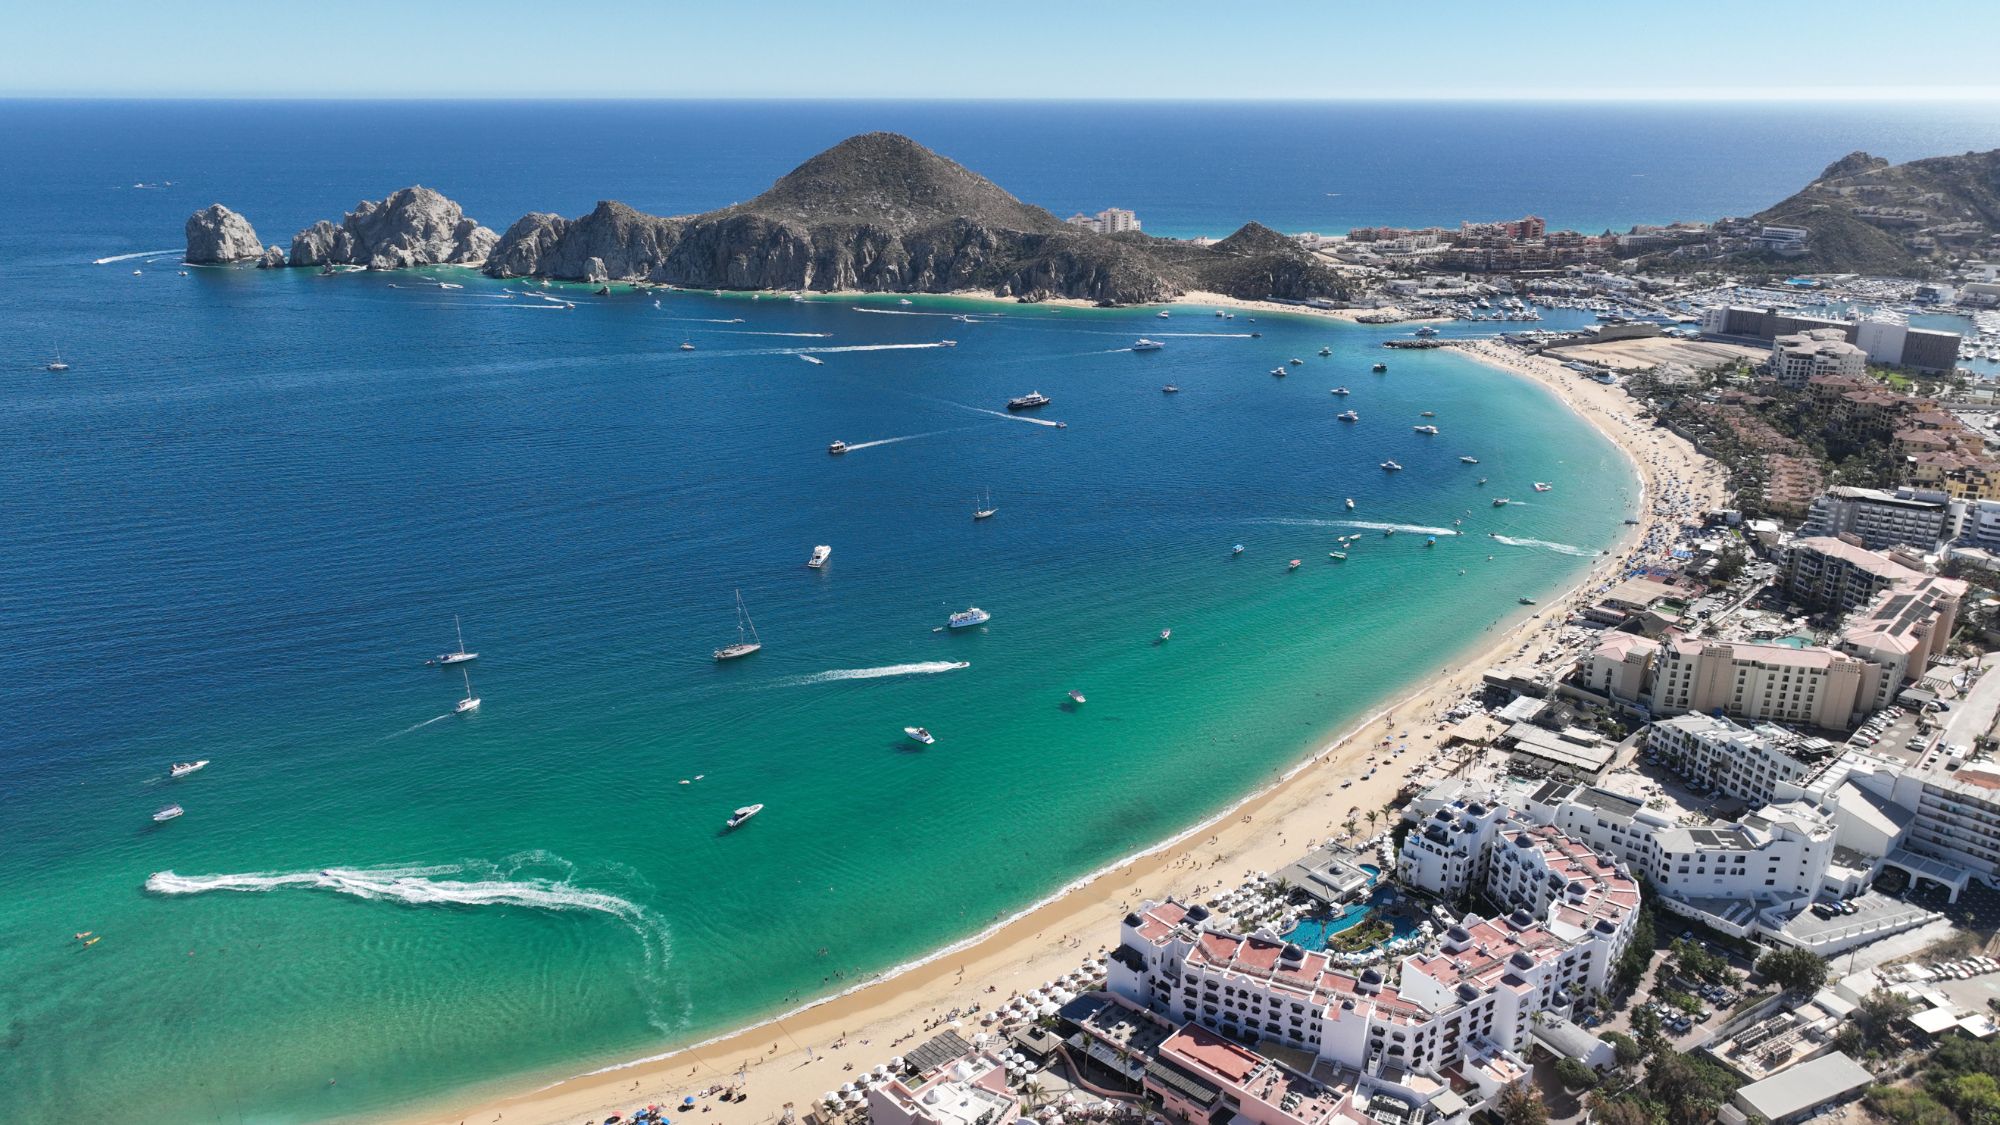
Most buyers who come to Los Cabos are already sold on the lifestyle — the Pacific views, the year-round sunshine, the fact that a direct flight from LAX or Dallas puts them here in under three hours. What they're often not prepared for is the number that shows up after the listing price.
That's not a warning to scare you off. It's the kind of information that makes the difference between a smooth closing and a stressful last-minute scramble. Here's exactly what you're paying for — and why every line item exists.
Why Closing Costs in Mexico Are Higher Than Most Buyers Expect
Buyers who've purchased in the U.S. or Canada are used to closing costs of 2% to 3%. In Mexico, the structure is different. Several fees exist specifically to protect the buyer — the notary system, the property registry, the appraisal requirement — and they're not optional.
The Full Breakdown: What the Buyer Pays
This is the largest single line item in your closing statement. Effective January 1, 2025, the Municipality of Los Cabos raised the Real Estate Transfer Tax — formally called Impuesto Sobre Adquisicion de Bienes Inmuebles (ISABI) — from 2% to 3%. Baja California Sur then harmonized the rate across all five municipalities, making 3% the standard throughout BCS as of January 1, 2026.
On a $400,000 USD purchase, that's $12,000 USD. On $700,000 USD it's $21,000 USD. It's a one-time tax, paid to the municipality at closing.
In Mexico, every real estate transaction must go through a licensed notary public. This isn't a formality — the notary is a government-appointed legal professional who certifies that the transaction is valid, verifies the title, and ensures the deed is properly registered.
If you're a foreign buyer purchasing property within 50 kilometers of the coast, Mexican law requires you to hold title through a bank trust called a fideicomiso. Since Los Cabos sits right on the coast, this applies to virtually every residential purchase here.
The bank holds legal title as trustee only. You, as beneficiary, retain full rights: use the property, rent it, renovate it, sell it, or pass it to your heirs. The bank cannot act without your explicit written instruction. The trust lasts 50 years and is fully renewable.
This is the category that tends to catch buyers off guard — not because any individual item is large, but because there are several of them:
- Certified property appraisal — required since 2025 for accurate ISABI calculation.
- No-debt certificate, predial — confirms no outstanding property tax balance.
- No-debt certificate, water services — confirms nothing owed to the water authority.
- Certificate of Freedom from Encumbrance (CLG) — certifies the current legal status of the property.
- Closing officer / transaction coordinator — manages all documentation, coordinates with notary and banks.
- Escrow fee — approximately $650 USD, held by a neutral third party until all conditions are met.
Before you sign anything, you should know exactly what you're buying. Due diligence includes a home inspection, a title search to confirm clean ownership history with no liens, boundary verification, and a legal review of HOA and condo regime documents when applicable.
This is money well spent — it's the stage where problems surface, and where the transaction can be renegotiated or exited cleanly if needed.
What the Seller Pays
For context — because buyers often ask — here's what falls on the seller's side:
| Seller Obligation | Notes |
|---|---|
| ISR — Capital Gains Tax | Federal tax on the profit from the sale |
| Real estate commission | Paid to the listing agent at closing |
| Fideicomiso cancellation | If the buyer is not assuming the existing trust |
| Outstanding utility balances | All services must be current at closing |
| Repairs from due diligence | If negotiated as part of the purchase agreement |
| Additional legal acts | Subdivision protocols, powers of attorney, etc. |
What's Actually Negotiable?
Honest answer: not much on the buyer's side. ISABI, notary fees, the appraisal, the technical certificates — these are set by law or by regulated third parties and cannot be negotiated down.
What is negotiable: repairs surfaced during the home inspection. This is the real leverage point. A skilled agent and a solid attorney can turn due diligence findings into meaningful concessions — price reductions, repair credits, or seller contributions.
The Real Numbers: What to Budget at Each Price Point
Working estimates for a foreign buyer purchasing with a new fideicomiso, paying cash.
| Purchase Price | ISABI (3%) | Notary (~1.25%) | Fideicomiso | Docs & Escrow | Due Diligence | Est. Total |
|---|---|---|---|---|---|---|
| $300,000 | $9,000 | $3,750 | $2,000 | $3,500 | $2,000 | ~$20,250 |
| $500,000 | $15,000 | $6,250 | $2,000 | $3,500 | $2,500 | ~$29,250 |
| $800,000 | $24,000 | $10,000 | $2,500 | $4,000 | $3,000 | ~$43,500 |
| $1,200,000 | $36,000 | $15,000 | $2,500 | $4,500 | $3,500 | ~$61,500 |
Estimates vary based on property complexity, choice of notary, and any legal contingencies.
Frequently Asked Questions
Yes. The legal mechanism is the fideicomiso (bank trust), which grants full ownership rights to foreign buyers in Mexico's coastal zones. It's a secure, well-established structure used by tens of thousands of international property owners across Baja California Sur.
In Los Cabos, the buyer is responsible for the majority: ISABI, notary fees, fideicomiso setup, technical documentation, escrow, and due diligence. The seller covers capital gains tax (ISR), the real estate commission, and costs related to their side of the transaction.
Typically 45 to 90 days from accepted offer to recorded deed, assuming a clean title and standard documentation. Pre-construction purchases operate under a different timeline and legal structure.
Completely. The bank acts as trustee in name only. You remain the sole decision-maker as beneficiary. The bank cannot sell, encumber, or act on the property without your explicit written instruction. Fideicomisos are 50-year renewable agreements and fully transferable to heirs.
As of 2025, Los Cabos sits at the upper end of the national range, driven primarily by the ISABI increase to 3%. Quintana Roo remains at 2%, while Tulum has moved to 4%. Total closing costs here typically run 5% to 9%, compared to 6%-10% in some competing coastal destinations.
The Bottom Line
A well-prepared buyer in Los Cabos isn't surprised at the closing table. They've already accounted for closing costs in their total acquisition budget, chosen their notary, completed due diligence, and know exactly what they're signing.
The market here is strong — 60% of properties sold in Los Cabos in 2025 were acquired by U.S. buyers, and demand continues to grow. Getting the most out of a Cabo transaction means understanding the full cost picture from day one.
Have Questions About a Specific Property?
Want a custom closing cost estimate before you make an offer? We're here to walk you through it.
Subscribe to Our NewsletterThis content is for informational purposes only and does not constitute legal or tax advice. We recommend working with a qualified Mexican attorney and tax advisor for your specific transaction.
Categories
Recent Posts